Keep using the property
The property stands as security while remaining yours and in your use.
 Fintech
Unlock the value of residential or commercial property you already own, through ANG-FINTECH’s network of partner banks and NBFCs.
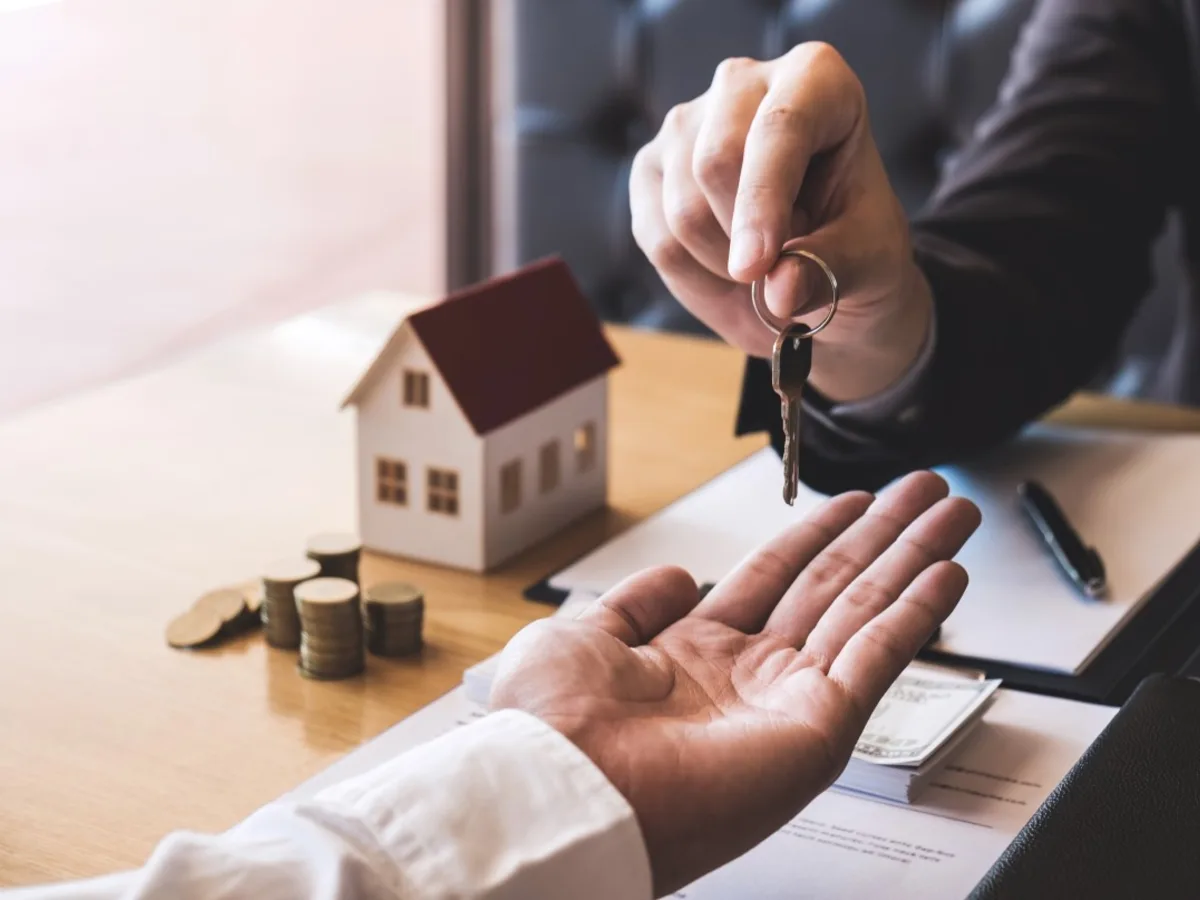
A loan against property (LAP) is a secured loan raised against a residential or commercial property you already own. The property continues to be yours and in your use; it stands as security for the borrowing.
Because the loan is secured by an asset, lenders assess both the applicant and the property itself, which is why property documents form part of the list below. ANG-FINTECH helps you assemble that file and route it to a suitable lending partner.
The property stands as security while remaining yours and in your use.
Eligible residential and commercial property can both be considered.
Salaried, self-employed professionals and self-employed non-professionals can apply.
The criteria below set out how co-applicants and legal heirs are treated.
Anyone can apply for a loan against property as long as they meet the criteria below.
Below are the documents required for completing your application process.
Five steps from first conversation to disbursal. Timelines and the final decision rest with the lending partner.
Tell us what you need and an advisor helps you shortlist a suitable lender.
Share your KYC, income and product-specific paperwork.
The lending partner reviews your profile and validates the documents.
Your application is processed by the partner bank or NBFC.
On approval, the sanctioned amount is released as per the lender’s terms.
Six core products, sourced across our network of partner banks and NBFCs.
Talk to an advisor about your requirement and we will help you find a suitable lending partner from our network.